On this page
The direct answer
Yes, an insurer can often require a separate roof-life certification for underwriting, but only when the request complies with applicable state law and the insurer’s approved rules. The exact authority, accepted form, inspector qualifications, and consequences of not providing it vary by insurer and jurisdiction.
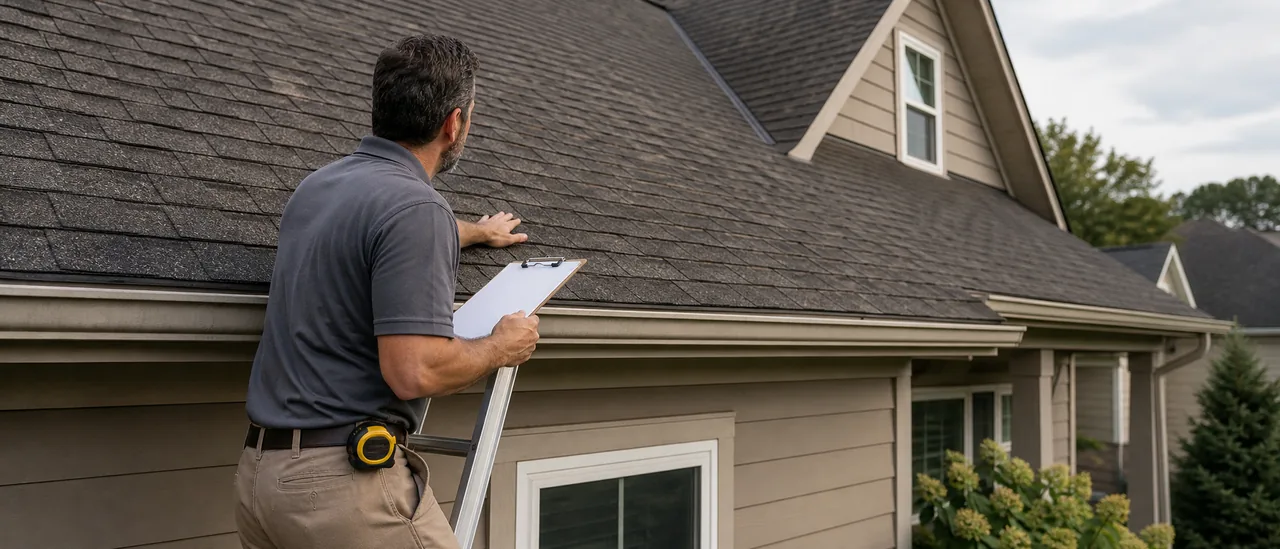
A “roof-life certification” is not a universal building-code document. In insurance use, it generally means a signed inspection record describing the roof’s age and condition and estimating its remaining useful life. An insurer may use it when deciding whether a home qualifies for a new or renewed policy.
Certification is not a guarantee
The document records an inspector’s professional opinion at a particular time. It does not promise how long the roof will last or establish coverage for a future loss.
Why an insurer may ask
Home insurers evaluate property characteristics during underwriting. The Texas Department of Insurance explains that companies use underwriting to decide whether to sell a policy and that their rules differ. Its consumer guide identifies a home’s age and condition among common considerations.
An insurer may already have a general home-inspection report, permit record, or installation receipt. It can still request a roof-specific form if those records do not answer its underwriting questions. A separate form may call for:
- roof-covering material and approximate age;
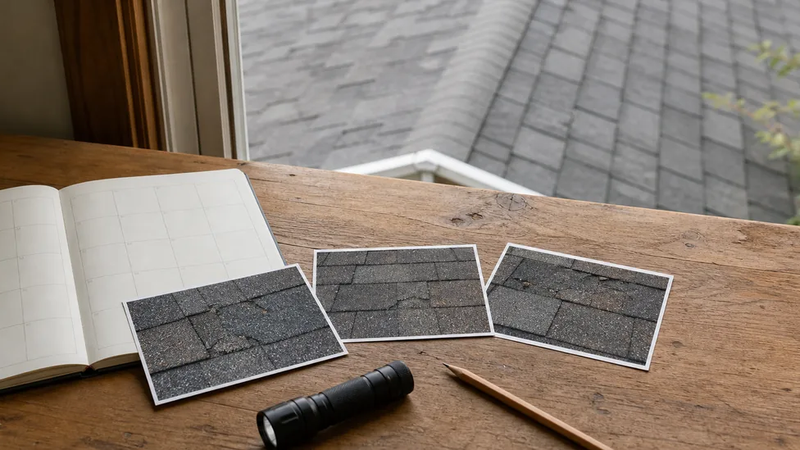
- visible deterioration, damage, leaks, or repairs;
- an estimate of remaining useful life;
- photographs; and
- the inspector’s license type, number, signature, and inspection date.
For example, Citizens Property Insurance Corporation’s Florida roof-condition form asks for those details, requires two roof photographs, and limits who may sign it to listed Florida-licensed professionals. That is evidence of one insurer’s documentation practice, not a nationwide rule.
The important limits
State law can restrict how roof age and inspection results affect eligibility. Florida law provides a useful example: for a roof at least 15 years old, an insurer must allow an inspection by an authorized inspector at the homeowner’s expense before requiring replacement as a condition of issuing or renewing a homeowners policy. If that inspection shows at least five years of useful life, the insurer may not refuse issuance or renewal solely because of roof age.
That Florida rule does not control policies elsewhere. Even there, it does not eliminate every lawful underwriting reason unrelated to age. The policy type, notice, requested form, inspector credentials, and current state requirements all matter.
Practical bottom line
Ask the insurer to identify the required form, deadline, acceptable credentials, and whether an existing report will satisfy the request. Read any nonrenewal or eligibility notice closely. If the demand or outcome appears inconsistent with state rules, the state insurance department can explain consumer rights and complaint procedures.