On this page
Yes, when the roof affects loan eligibility
Yes, a lender can require roof repairs before closing when the property must meet the lender’s or loan program’s condition standards. The requirement usually makes completion of the repair, an acceptable inspection, or both a condition of funding—not an automatic command that the seller personally perform or pay for the work.
The issue commonly begins with an appraisal. Fannie Mae’s Selling Guide requires appraisals to identify apparent adverse conditions and items needing immediate repair. When a deficiency could affect safety, soundness, or structural integrity, its guidance calls for the appraisal to be completed “subject to” correction.
Minor wear does not always produce the same result. Fannie Mae permits an “as is” appraisal when existing conditions are minor, do not affect safety, soundness, or structural integrity, and are reflected in the appraiser’s value opinion.
A financing condition is not a repair contract
The lender decides whether the collateral meets its requirements. The purchase agreement, inspection provisions, amendments, and applicable law determine who agreed to arrange or pay for repairs—and what options remain if the condition cannot be satisfied.
What changes the answer
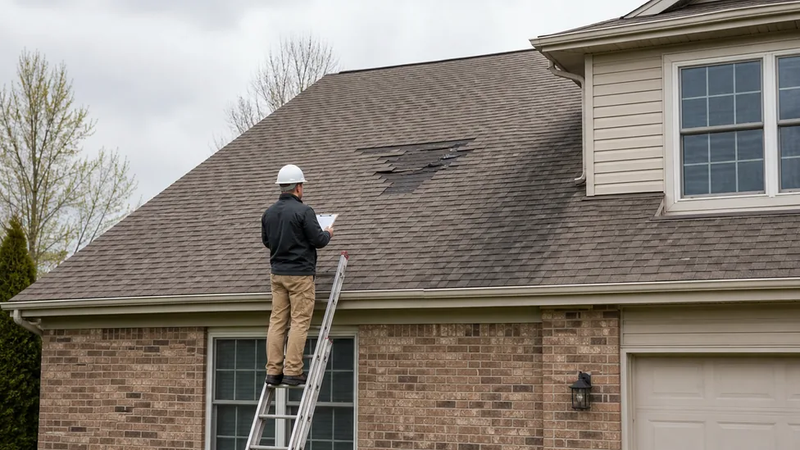
A repair condition is more likely when a report documents active leakage, serious deterioration, or structural concerns. Roof age alone does not establish a required repair; documented condition and the applicable underwriting standard matter.
The practical outcome depends on several transaction-specific facts:
- the loan program and the lender’s underwriting requirements;
- the appraiser’s stated condition and any required follow-up inspection;
- whether a qualified professional must evaluate the roof;
- the purchase contract’s repair, financing, notice, and termination provisions; and
- whether the lender allows any program-compliant method for completing work after closing.
Do not assume an escrow holdback or repair credit will solve the condition. Permission depends on loan rules, lender approval, the defect, and closing documents.
What happens before closing
The parties first need the lender’s condition in writing. It should identify whether the file requires a repair, a roof inspection, evidence of completion, a reinspection, or a combination of these.
If the appraiser is not qualified to evaluate a reported deficiency, Fannie Mae guidance allows the appraisal to be conditioned on a satisfactory inspection by a qualified professional. The lender then decides whether the inspection is required and whether the property is eligible.
The buyer and seller can negotiate who arranges and funds permitted work, but cannot force the lender to fund a loan that fails underwriting. If the condition remains unresolved, closing may be delayed or financing denied; contractual rights then depend on signed documents and local law.
Before changing deadlines, authorizing repairs, or releasing contingencies, obtain the written lender condition, the complete appraisal or inspection requirement, and the purchase-contract provisions. Have the lender confirm what will satisfy underwriting, and use a qualified roof inspector and local real-estate attorney when the condition or contractual remedy is unclear.