On this page
Start with the cost of the defined roof work
A roof credit should be calculated from the current, documented cost of the roof work the property needs. Start with an inspection-defined scope, price that same scope through written estimates, subtract work already paid for or completed, and then apply any financing or closing limits.
It is not automatically the roof’s full replacement price. It also is not a standard percentage based on age. A repairable flashing defect and a roof requiring complete replacement create different scopes, even when the coverings are the same age.
A practical calculation
Roof credit basis = priced required scope + documented related costs − work already completed or funded elsewhere. The usable closing credit may be lower if the contract or loan program limits it.
Build a comparable cost basis
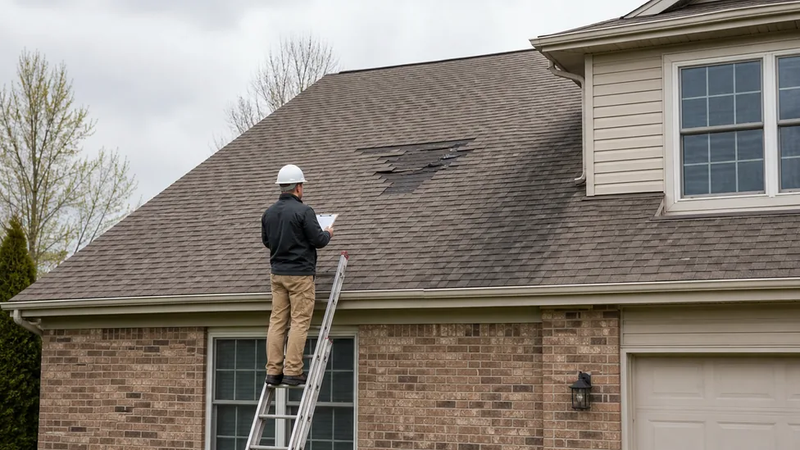
First, have a qualified roof inspector or roofing professional identify whether the scope is a localized repair, a larger repair, or replacement. The finding should name affected components and any access limitation. Unknown deck damage can be listed as a unit-price allowance rather than treated as a confirmed cost.
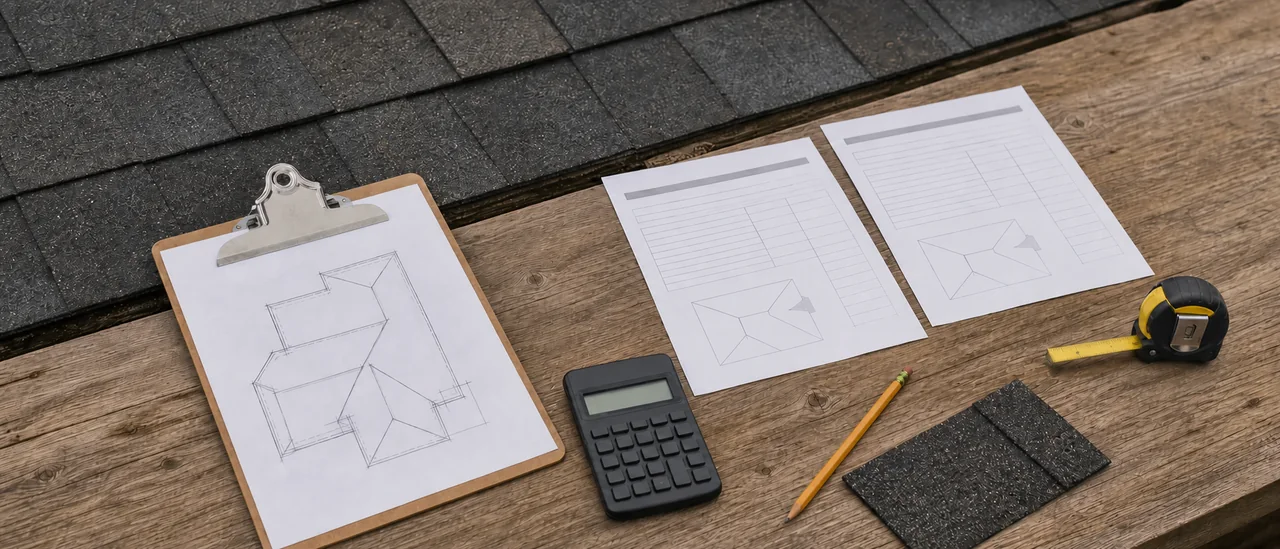
Next, compare written estimates covering the same work. The Federal Trade Commission says an estimate should describe the work, materials, completion date, and price. It also advises against automatically choosing the lowest bidder. Normalize these items before comparing totals:
- roof area, material, and number of existing layers;
- tear-off, underlayment, flashing, and ventilation work;
- known deck repairs and separately stated allowances;
- permits, disposal, taxes, and required inspections.
Local requirements can materially change the total. For example, Jefferson Parish’s published residential reroof process includes a permit, removal of existing material, water-resistant underlayment, drip edge, flashing, and the new covering. That example is not a nationwide rule; the applicable jurisdiction and manufacturer instructions control the actual project.
Do not average bids with different scopes. Reconcile the differences first, then use a current estimate that reasonably represents the required work. Exclude elective upgrades unless they are necessary for compatibility or compliance.
Apply transaction limits separately
The technical cost basis and the amount usable at closing are not always identical. For mortgages governed by Fannie Mae rules, financing concessions are capped by occupancy and loan-to-value criteria, calculated from the lower of the sale price or appraised value. They also cannot exceed the borrower’s closing costs without different underwriting treatment.
CFPB’s Closing Disclosure explainer says a general seller credit appears as the amount contributed toward closing costs. Payment of a specific cost may instead appear as a seller-paid line item. The lender or settlement professional should confirm how the roof amount can be documented and used in that transaction.
Practical bottom line
Calculate the roof credit from a clearly defined, currently priced scope—not a guess about age or remaining life. Keep the inspection, comparable estimates, allowances, and exclusions together. Then confirm the final usable amount against the written transaction terms and financing rules.