On this page
Choose based on certainty, control, and cash
Ask for repairs when the roof problem is clearly defined, needs correction before closing, and the completed work can be documented and checked. Ask for a credit when you want to control the work after closing and the credit can actually cover permitted closing costs. Favor a price reduction when long-term affordability matters more than cash available immediately.
The answer changes when the defect may affect the loan or property eligibility. In that situation, a credit or lower price may not replace work that must be completed before closing. Confirm the lender’s requirements before choosing.
Compare what each option actually does
| Option | Strongest fit | Main limitation |
|---|---|---|
| Seller repairs | Defined work that must be finished before closing | The seller controls contractor selection and scheduling unless the agreement says otherwise |
| Seller credit | Buyer wants control and has enough money after closing to complete the work | A credit generally reduces cash due at closing; it does not repair the roof or necessarily provide repair funds |
| Price reduction | Buyer can fund the work and values a smaller purchase price | The monthly-payment change may be modest, while the repair bill arrives much sooner |
A seller credit is not automatically equal to cash for a roof project. The Consumer Financial Protection Bureau explains that a seller contribution to closing costs reduces costs at closing, but the buyer still must pay for the repair afterward. It also cautions that a higher price used to support a credit can create an appraisal problem.
When to request repairs
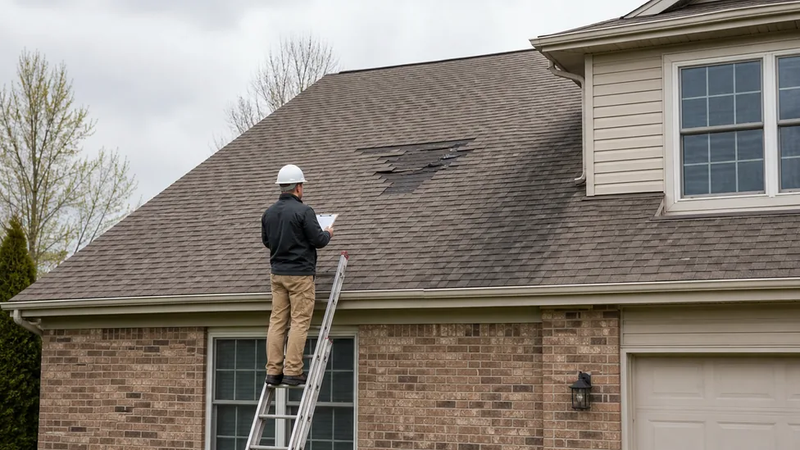
Repairs are the better request when active leakage, an open penetration, missing materials, or another documented condition should not remain through closing. The written scope should identify the affected area, materials, responsible contractor, completion deadline, permits when applicable, and evidence of completion.
Avoid a vague promise to “fix the roof.” That wording does not establish whether the work is a temporary patch, a limited repair, or replacement of a larger section. A receipt alone also shows payment, not necessarily that the documented defect was corrected.
Resolve the scope before choosing the remedy
An inspection observation is not always a repair specification. If the cause, affected area, or appropriate correction remains uncertain, obtain a written evaluation and scope first. Otherwise, every dollar comparison rests on a guess.
When a credit makes more sense
A credit can preserve buyer control over contractor selection, materials, and timing. It works best when the roof is serviceable through closing, the repair scope is reasonably known, and the buyer can cover any difference between the credit and the final invoice.
Before relying on one, ask the lender and closing professional where the credit may appear, whether it is limited, and what happens if eligible closing costs are lower than expected. The contract should also state the agreed amount and purpose clearly. Those details vary with the transaction, so a verbal understanding is not enough.
Build uncertainty into the decision. An estimate based only on visible conditions may change after roofing is removed. If the credit uses the lowest preliminary estimate with no contingency, the buyer accepts that difference.
When a price reduction is the cleaner choice
A lower price is useful when no pre-closing repair is required and the buyer already has sufficient funds for the work. It reduces the amount paid for the property, but it does not usually create a dollar-for-dollar pool of cash at closing.
Compare the expected repair payment with the actual change in down payment, loan amount, and monthly payment—not just the headline reduction. If immediate cash is the constraint, a price reduction may solve the wrong problem.
Documents to settle the choice
Use a roof evaluation that describes observed conditions, limits of access, recommended work, and urgency. Pair it with a detailed estimate, the purchase-contract terms, and written confirmation of lender or closing constraints. When the roof scope is uncertain or a pre-closing repair may be required, a qualified roof evaluation is the practical next step.