On this page
Yes, but the lender makes the final call
Yes—an appraiser can make an appraisal subject to roof repairs, but the lender and applicable loan rules determine whether those repairs become a financing condition. The appraiser documents visible deficiencies and states the assumptions behind the value opinion; the appraiser does not personally compel an owner to repair the roof.
This distinction matters because “required by the appraiser” is common shorthand. In practice, the appraisal report may identify an immediate repair, call for a qualified roof inspection, or value the property as though specified work were complete. The lender then reviews the report against its property-eligibility rules.
When a roof issue can trigger a condition
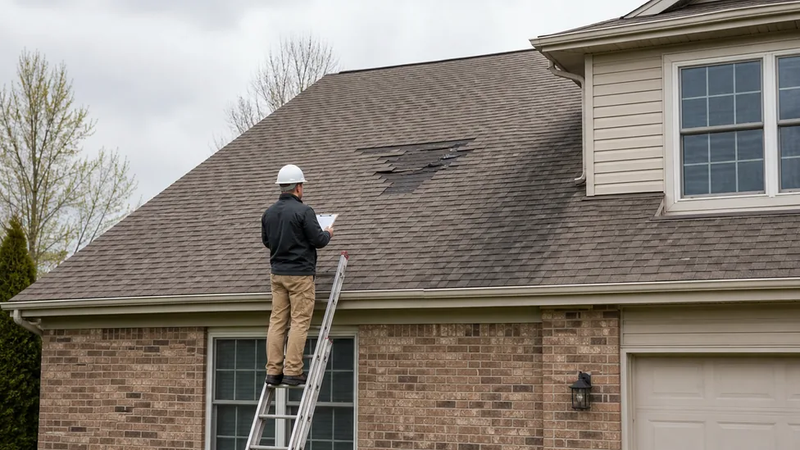
A visible roof problem is most likely to affect the appraisal when it may threaten safety, soundness, or structural integrity. Fannie Mae requires an appraisal to be completed “subject to” correction when a physical deficiency could affect those qualities. If the appraiser is not qualified to evaluate the condition, the report may instead be subject to a satisfactory inspection by a qualified professional.
That does not mean every worn shingle produces a repair condition. Fannie Mae permits an “as is” appraisal when existing conditions are minor and do not affect safety, soundness, or structural integrity. The appraiser must still report needed repairs and deferred maintenance and account for the property’s condition in the value opinion.
“Subject to inspection” is not the same as “repair required”
A roof inspection may show that no repair is necessary. When specialized evaluation is needed, the lender decides whether to require that inspection and whether the resulting evidence satisfies its eligibility rules.
What the appraiser can—and cannot—determine
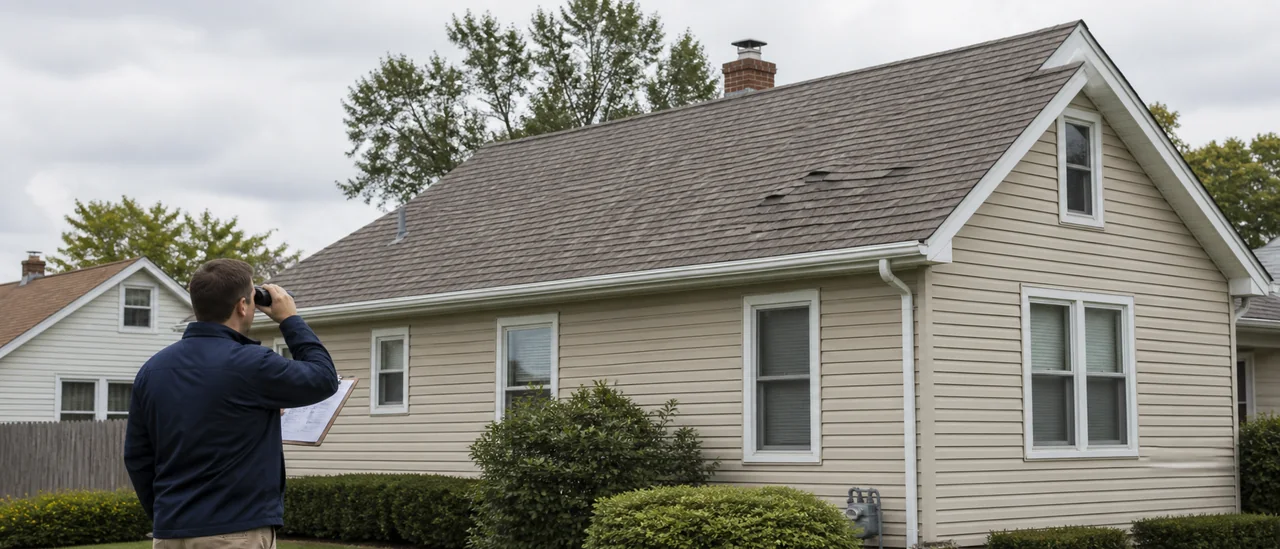
An appraisal is a valuation assignment, not a comprehensive roof inspection. For an appraisal involving interior and exterior inspection, the appraiser visually reviews accessible areas and reports apparent adverse conditions. Hidden or unapparent conditions are outside that responsibility.
The practical result can vary with the observed condition, appraisal scope, lender, and mortgage program. A report can be accepted as-is, conditioned on specific repairs, or conditioned on further inspection. If work is required, the lender may also request evidence that it was completed before the loan meets the applicable program’s requirements.
Practical bottom line
Read the appraisal’s reconciliation and condition comments closely. They should show whether the value is as-is, subject to repair, or subject to inspection. Then ask the lender which item is an actual loan condition and what documentation will clear it. That separates the appraiser’s observation from the lender’s financing decision.
Related reading: Can a lender require roof repairs before closing?